Government Bonds vs. Corporate Bonds: How to Pick the Right Yield
This guide helps you decide between Government Bonds vs. Corporate Bonds based on your specific financial situation. It moves beyond basic definitions to provide a structured evaluation process for aligning bond selection with your unique risk tolerance and income goals.
You will learn how to assess Sovereign Debt stability against Credit Risk, compare Yield to Maturity, and understand the impact of Tax-Exempt Interest. The focus is on actionable steps to optimize your portfolio’s balance of security and return.
By the end, you will have a clear framework for choosing the right yield, avoiding common pitfalls, and constructing a bond allocation that fits your long-term objectives without guesswork.
Define Your Risk Tolerance and Income Needs
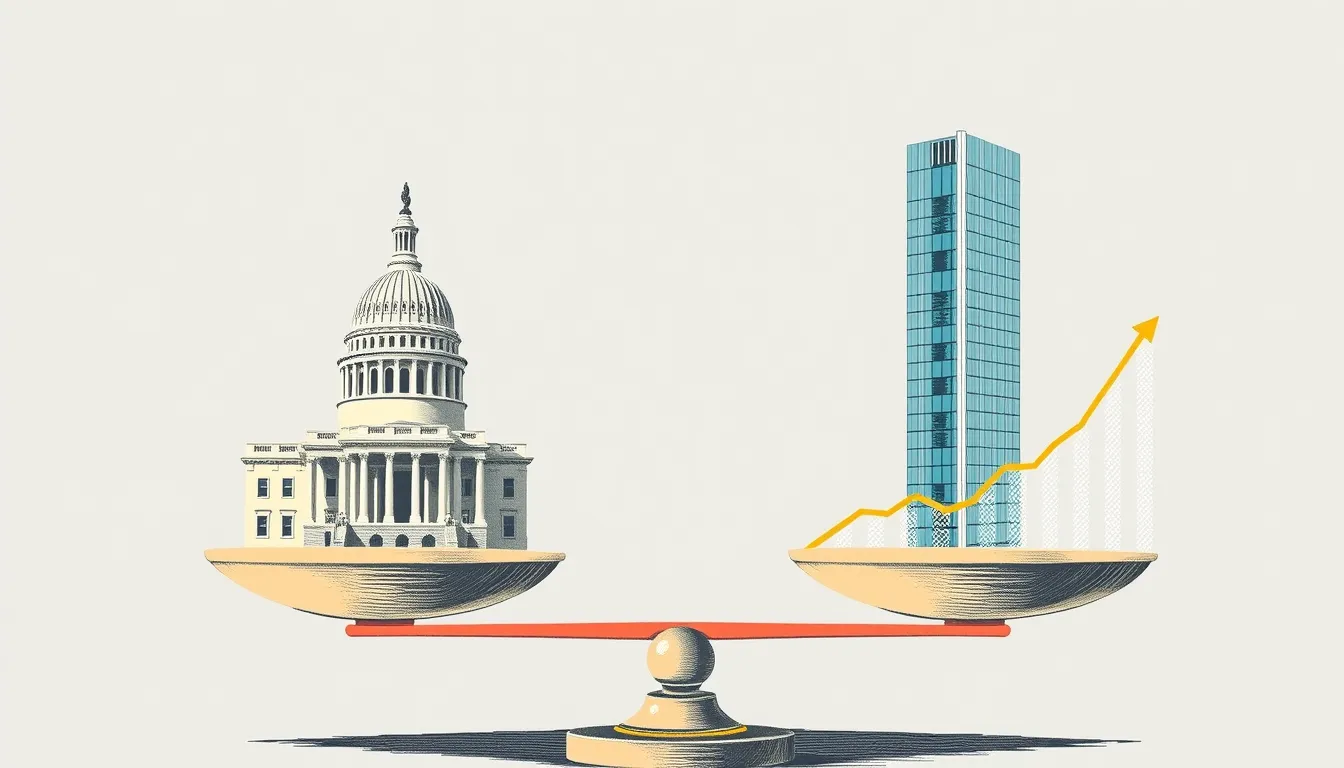
Before comparing specific issuers, establish your financial baseline. Government bonds, backed by Sovereign Debt, typically offer lower risk and correspondingly lower Yield to Maturity. Corporate bonds carry higher Credit Risk, demanding a higher yield to compensate for the increased Default Probability. Your choice depends on how much volatility you can absorb and your immediate cash flow requirements.
Ask yourself if your primary goal is protecting your principal or generating additional income. If you cannot tolerate significant price swings or capital loss, you are oriented toward capital preservation. In this case, the stability of government securities aligns with your needs. If you can withstand short-term market fluctuations in exchange for higher periodic payments, you are oriented toward income growth. Here, the higher yield from corporate debt may be appropriate.
This categorization dictates your subsequent steps. A capital preservation focus prioritizes low Default Probability and high liquidity. An income growth focus accepts higher Credit Risk to maximize Yield to Maturity. Do not skip this assessment. Misidentifying your orientation leads to mismatched expectations during market downturns. Determine whether you need steady, predictable cash flow or are willing to accept variable returns for greater potential income. Once you identify your orientation, you can filter bond options accordingly, ensuring your portfolio structure supports your specific risk capacity and financial goals.
Evaluate Credit Risk and Default Probability
Government bonds derive their value from the taxing power of the sovereign state, making them the benchmark for safety in the market. In contrast, corporate bonds rely entirely on the issuer’s operational performance and financial stability. This fundamental difference in backing creates a distinct hierarchy of Credit Risk. When evaluating Sovereign Debt, the primary concern shifts from solvency to macroeconomic factors, whereas corporate issuers face direct Default Probability tied to their business cycles.
Credit ratings serve as the primary filter for this analysis. Agencies assess an issuer’s ability to meet obligations, assigning grades that reflect the likelihood of default. Higher-rated government issues typically command lower yields due to minimal perceived risk. Conversely, corporate issuers must offer a premium to attract capital, compensating investors for the inherent uncertainty. This yield spread is not a bonus but a necessary offset for the additional risk assumed.
Understanding this dynamic is critical. If you select corporate bonds without accounting for their specific Credit Risk profile, you may underestimate potential losses during financial distress. The higher Yield to Maturity offered by corporates is only justified if you have thoroughly vetted the issuer’s balance sheet and industry position. By recognizing that corporate bonds carry inherent default risk, you can accurately weigh whether the extra income justifies the exposure. This clarity prevents mispricing your portfolio’s overall risk level.
Compare Yield Structures and Tax Implications
Now shift focus to the net return you will actually pocket. While corporate bonds often display a higher nominal Yield to Maturity, sovereign debt—especially U.S. municipal bonds—can provide Tax‑Exempt Interest that lowers the effective tax bite.
- Calculate the after‑tax yield. Multiply the bond’s nominal yield by (1 – your marginal tax rate) for taxable corporate issues, then compare that figure to the tax‑exempt yield of the government bond. Result: a level playing field for side‑by‑side comparison.
- Adjust for the Liquidity Premium. If the corporate bond trades in a less liquid market, add a modest premium to its after‑tax yield to reflect the extra risk of selling before maturity. Result: a more realistic assessment of expected income.
- Identify the higher net return. The bond with the greater after‑tax yield—whether it is a lower‑nominal, tax‑exempt sovereign debt or a higher‑nominal corporate issue—wins the yield comparison. Result: you select the bond that truly maximizes income for your tax situation.
Common mistake: assuming a higher nominal yield always means higher net income without adjusting for taxes or liquidity. This can lead to overpaying for taxable corporate bonds when a tax‑exempt government bond would deliver more after‑tax cash.
Assess Liquidity and Market Volatility
When you anticipate the possibility of selling a bond before it reaches maturity, the ease of exiting the position becomes a decisive factor. Sovereign debt typically trades in deep, highly active markets, meaning you can convert a government bond to cash with minimal price impact and a narrow bid‑ask spread. This built‑in liquidity reduces the need for a large liquidity premium.
Corporate bonds—especially issues from mid‑size or smaller issuers—often sit in thinner markets. Their prices can swing sharply on changes in market sentiment, and the bid‑ask spread widens, forcing you to accept a lower price if you need to sell quickly. The extra compensation investors demand for this risk is reflected in a higher liquidity premium embedded in the Yield to Maturity.
To decide which bond class aligns with your cash‑flow flexibility, ask yourself: “Do I need the option to liquidate within the next 12‑24 months?” If the answer is yes, the predictable liquidity of government bonds generally outweighs the potentially higher nominal yield of corporate issues.
- Common mistake: Assuming a corporate bond’s higher Yield to Maturity automatically offsets the cost of a wider spread when you sell early.
- Common mistake: Ignoring market volatility and treating all corporate bonds as equally liquid, which can lead to unexpected losses in a stressed market.
Construct a Balanced Bond Allocation
Blend for Balance
Most investors benefit from holding both asset classes rather than choosing exclusively. This approach creates a diversified bond portfolio that mitigates the specific risks inherent in each. Start by establishing a stable core using Sovereign Debt. These government bonds provide consistent income and low Default Probability, anchoring your portfolio during market stress. Use this foundation to absorb volatility without compromising your principal.
Next, layer in corporate bonds to enhance yield. Select issues with manageable Credit Risk that align with your income goals. The additional return helps offset the lower payouts from your sovereign holdings. Aim for a mix where the aggregate Yield to Maturity meets your target income level while keeping overall Credit Risk within your tolerance.
Consider the tax impact of this blend. If you hold Tax-Exempt Interest from municipal debt, it may replace some corporate exposure in tax-sensitive accounts. Adjust the ratio based on your Liquidity Premium needs. A balanced allocation ensures that if corporate spreads widen, your sovereign core remains liquid, and if interest rates shift, your mixed duration profile cushions the impact. This strategy transforms individual bond strengths into a cohesive income engine.
Common Mistakes to Avoid in Bond Selection
Common Mistakes to Avoid in Bond Selection
Many investors overlook inflation risk, assuming fixed coupons preserve purchasing power. In reality, rising prices erode the real value of Sovereign Debt returns, making nominal yield insufficient for long-term goals. Always assess how expected inflation impacts your required Yield to Maturity.
Another frequent error is treating all corporate bonds as identical. High-yield issuers carry significantly higher Default Probability than investment-grade counterparts. Confusing these categories leads to underestimating Credit Risk. Distinguish between speculative and stable issuers before allocating capital, as their volatility profiles differ drastically.
Chasing the highest headline yield without examining credit quality is a dangerous pitfall. A slightly lower yield on a high-grade bond often offers better risk-adjusted returns than a volatile high-yield instrument. Prioritize safety and consistency over peak nominal returns.
Finally, ignoring interest rate sensitivity distorts portfolio value. As rates rise, bond prices fall. Failing to account for duration means you may sell at a loss during market corrections. Align your maturity ladder with your cash flow needs to mitigate this price volatility.